Best Money Apps in 2026: Cash App Guide & More
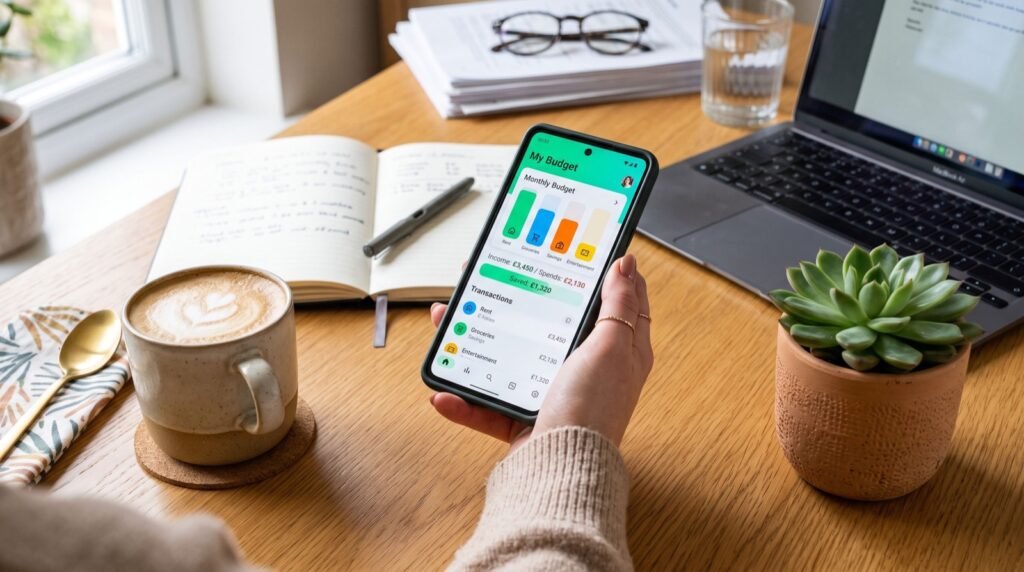
Choosing the best money apps in 2026 means weighing speed, security, and fees across a crowded field of mobile wallets, budgeting tools, and peer-to-peer payment platforms. Whether you’re splitting rent, paying a freelancer, or just trying to track where your paycheck actually goes, the right app can save you real money and real time.
The mobile payments market has only gotten more crowded this year, which makes picking wisely harder, not easier. This guide breaks down what actually matters when comparing apps, walks through a practical Cash App guide for first-time users, and gives you a side-by-side table so you’re not guessing.
Why the Best Money Apps Matter More in 2026
Cash is disappearing from everyday transactions faster than most people realize. Rent splits, side-hustle payouts, refunds between friends, and even tipping now happen almost entirely through apps. That shift puts pressure on consumers to understand transfer limits, hold times, and dispute processes before a problem arises — not after.
Fee structures also vary wildly. Some platforms charge nothing for standard transfers but add a percentage for instant deposits. Others bundle in budgeting, savings, or even basic investing features, which can replace two or three separate apps with one.
What to Look for in Mobile Money Apps
Not all mobile money apps are built the same, and the differences matter more than the marketing suggests. Before picking one, run through a short mental checklist.
- Transfer speed — standard (1-3 days) vs. instant (fee-based, usually 0.5-1.75%)
- FDIC insurance or equivalent protection on stored balances
- Clear, published fee schedules with no hidden currency-conversion markups
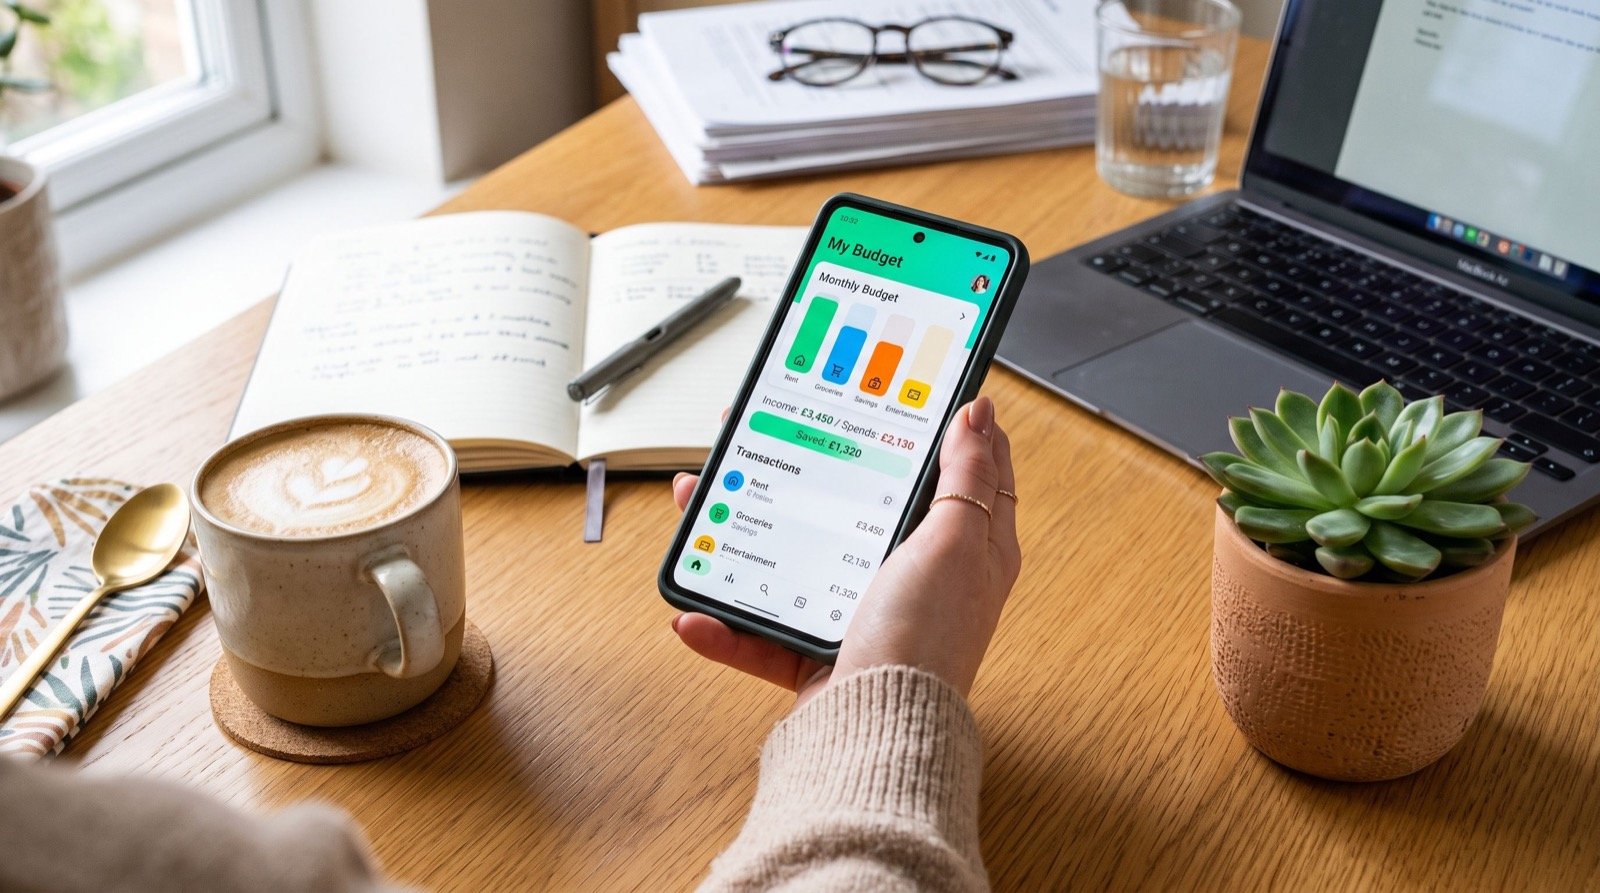
- In-app budgeting, round-up savings, or early paycheck access
- Responsive fraud dispute and account-recovery support
If an app clears those five points, it’s worth testing with a small balance before relying on it for regular use. For a broader shortlist of best money apps, compare at least three before committing — pricing and features shift often enough that last year’s favorite isn’t always this year’s best fit.
A Quick Cash App Guide for Beginners
Cash App remains one of the most widely used peer-to-peer platforms, and understanding its basics prevents most of the common frustrations new users hit. This Cash App guide covers what actually matters before you link a card.
Setting Up Safely
Verify your identity fully before moving any significant amount of money. Unverified accounts face lower sending and withdrawal limits, and support escalations take longer to resolve if something goes wrong early on.
Avoiding Common Scams
Most Cash App fraud doesn’t come from a hacked account — it comes from a sender tricked into paying a stranger directly. The Federal Trade Commission’s consumer guidance on payment apps is blunt about this: treat peer-to-peer transfers like cash. Once sent, they’re nearly impossible to reverse. Read the FTC’s guide on safely using payment apps before you start sending money to people you haven’t met in person.
Comparing the Best Money Apps of 2026
| App Type | Typical Transfer Fee | Best For |
|---|---|---|
| P2P Payment App | Free standard / 0.5-1.75% instant | Splitting bills, quick transfers |
| Budgeting App | Free to $10/month | Tracking spending, building savings habits |
| Digital Banking App | Usually free | Everyday checking, direct deposit |
| Investing App | Varies, often $0 trade commission | Beginners starting small, round-up investing |
Switching Apps Without Losing Track of Your Money
People rarely stick with their first money app forever. Fees change, a better rewards structure launches somewhere else, or a bank account gets replaced after a move. The mistake most people make when switching is doing it all at once, mid-month, while bills are still routed to the old account.
A Safer Way to Migrate Balances
Run both apps in parallel for one full billing cycle before closing anything. Update direct deposit information first, confirm at least one full paycheck has landed in the new account, and only then start redirecting autopay subscriptions one at a time. Closing an old account too early is one of the most common causes of a missed bill or a declined payment right after a switch.
It also helps to export a transaction history from the old app before closing it. Most platforms only retain historical statements for a limited window after an account closes, and you may need that record later for taxes, a dispute, or a loan application.
Are Money Apps Actually Safe to Use?
Yes, provided you pick apps backed by FDIC-insured partner banks and you follow basic hygiene: strong unique passwords, two-factor authentication, and never sharing one-time codes. The risk usually isn’t the app itself — it’s how users interact with strangers through it.
If you’re relocating this year, money-app setup is often one of many logistics items on the list. Families coordinating an apartment move, for example, frequently handle deposit transfers and moving-cost splits through these same apps, which is one more reason to have reliable tools lined up before move-in day. Working with an experienced local team for the physical move pairs well with having your financial apps already sorted out.
Frequently Asked Questions
What is the safest money app to use in 2026?
There’s no single “safest” app for everyone, but apps backed by FDIC-insured partner banks, offering two-factor authentication and transaction alerts, consistently rank highest for security among mainstream options.
Do money apps charge hidden fees?
Reputable apps publish their fee schedules clearly, but instant-transfer fees, currency conversion markups, and out-of-network ATM charges are easy to miss if you don’t read the fine print before signing up.
Can I use more than one money app at once?
Yes, and many people do — one for everyday P2P transfers, another for budgeting, and a third for savings or basic investing. Just keep track of which balances sit where to avoid overdraft surprises.
Is Cash App better than a traditional bank account?
They serve different purposes. Cash App and similar apps excel at fast peer-to-peer transfers, while traditional accounts still offer stronger protections for larger balances, loans, and long-term savings products.
Final Thoughts on Choosing the Right App
The best money apps in 2026 aren’t necessarily the flashiest ones — they’re the ones that match how you actually spend, save, and send money day to day. Start with the checklist above, test with a small balance, and don’t be afraid to run two apps side by side until one clearly wins out. A little diligence now saves a lot of frustration later.
One habit worth building regardless of which app you settle on: review your linked accounts and active permissions every few months. People accumulate old connections from trial sign-ups, one-off transfers, and apps they stopped using years ago, and each one is a small, unnecessary surface for something to eventually go wrong. A quarterly five-minute audit costs almost nothing and closes a lot of quiet risk.